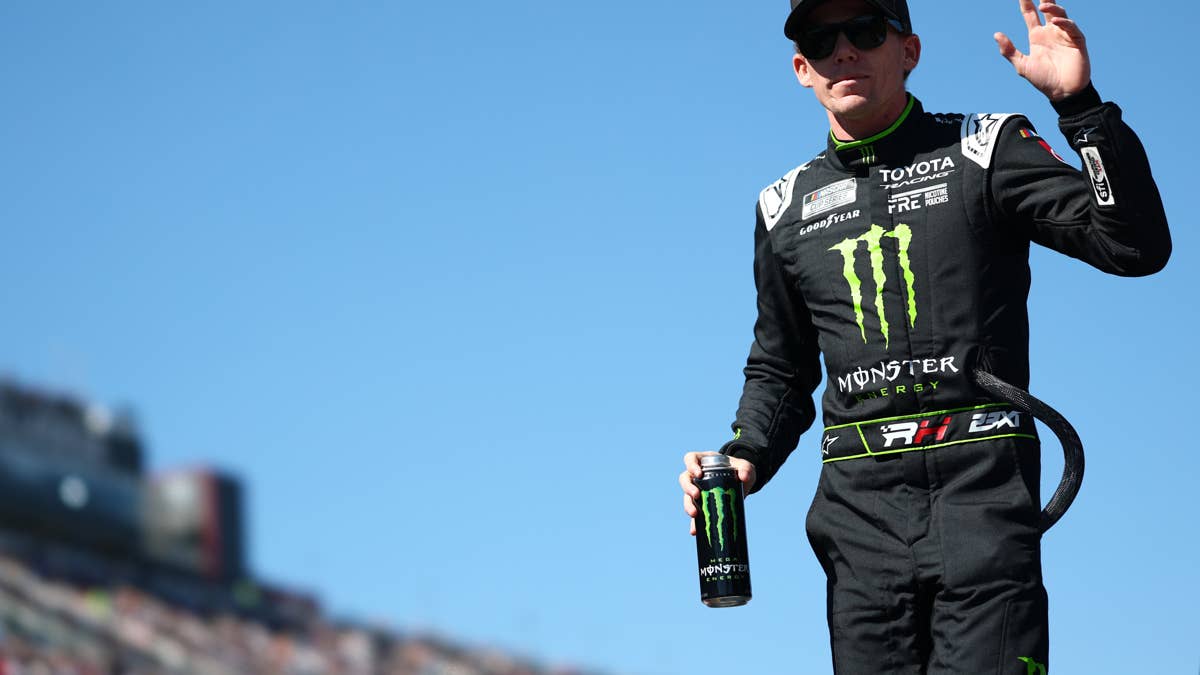

I drink Monster Energy myself. So I understand why the brand has built such a loyal following.
It’s one of those few products people can keep coming back to, even as prices change. That loyalty helps explain why Monster continues to grow across markets, despite pressure from higher production costs.
I’m clearly not the only one. Monster Beverage (MNST) grew third-quarter net sales 16.7% to $2.56 billion, and sales outside the U.S. jumped 28.1% to $1.20 billion, representing 47% of total net sales.
In 2025, Monster Beverage recorded a record $8.3 billion in net sales, extending its streak of annual revenue growth to 33 consecutive years. Red Bull is still bigger, with record sales of €12.2 billion, nearly double Monster’s.
In its Q3 2026 earnings call, CEO Hilton Schlosberg said higher prices would not deter consumers, calling the drinks an “affordable luxury” that compares well with pricier options such as coffee. However, the cans cost Monster more to make.
Also: Monster Energy discontinuing 12 energy drinks
Monster’s sales surge, but the bar is high
Shared with me at TheStreet, Morgan Stanley kept an Overweight rating and its $55 price target on Monster in a note titled “Reiterate OW: Passport to Topline Growth, With GM Inflection Still to Come.”
The note notes third-quarter sales growth, excluding currency effects, came in at 16.3%, 3.6 points above Wall Street’s forecast. International sales grew 27.2% and U.S. sales 8.2%, slightly above expectations.
More Beverages:
- Warren Buffett, 96, credits Coke and McDonald’s for his long life
- Pepsi shuts down another U.S. plant as CEO admits soft drink slump
- Warren Buffett bought this company in 1988 when ‘no one’ wanted it — now it pays Berkshire $848 million a year
The momentum continued into October, with sales up about 15% after adjusting for the number of days, though U.S. store checkout data showed some moderation. The note still notes the stock has risen more than 40% over the past year, so the bar is high.
Shares are up 18.27% this year, compared with 9.87% for the S&P 500, and up 29.49% over one year, compared with 10.08%, according to Yahoo Finance.
What’s squeezing Monster’s margins
Gross margin, the share of each sale left after making the product, missed forecasts by about 0.7 points and fell about 1.1 points from a year ago.
Morgan Stanley estimates the entire decline originated from geography, since faster-growing international sales carry lower margins. Pricing largely covered the higher cost of aluminum and other inputs.
Aluminum is the sore spot. S&P Global Energy found that the U.S. Midwest Premium for aluminum was up 186.5% from year-ago levels as of April, after tariffs and Middle East disruptions.
Related: Shopify’s booming sales come with a costly catch
In its Q3 2026 earnings call, Monster executives said they expect costs to keep rising modestly through at least the end of 2026. That is why the company raised U.S. prices by a mid-single-digit percentage on Nov. 1, as well as selected prices in Europe, the Middle East, and Africa.
As someone who drinks Monster, I wouldn’t notice if the price increased. But I would if it were a regular purchase. Sometimes loyal customers accept a small price increase rather than give up a favorite brand.
The growth is worldwide. According to its Q3 2026 earnings call transcript, Latin America sales rose 40%, led by Brazil, up 60.4%. Europe, the Middle East, and Africa grew 25.1%. In Asia-Pacific, China rose 35.5%, and India rose 86.5%, even with labeling hurdles. Spending also rose, including on a digital overhaul ahead of a January 2028 software go-live.
Morgan Stanley expects margins to recover in 2027
Morgan Stanley expects a margin turn that Wall Street doesn’t expect in 2027 as aluminum and mix pressure fade. Pricing, a shift toward higher-margin zero-sugar drinks, and cost savings should help. Europe’s gross margin ticked up to 37.2%, and Latin America’s rose to 47.7%.
2027 brings fewer launches but more focus for shoppers: phased January releases, Monster Protein in March, and Monster Energy McLaren Zero Sugar in summer.
The $55 target rests on about 35x 2028 earnings, unchanged after the quarter. The question now is whether growth and pricing outrun costs after a big run. For everyone else, the price on the can is the visible part of that story.